Last Updated: November 4, 2026
Quick Summary
A mental health practice financial policy is a written document that tells clients how the practice charges for services, when payment is due, and what happens when things go wrong. It covers session fees, payment timing, insurance responsibilities, cancellation charges, and steps for unpaid balances, protecting both the practice and the client.
- Cover session fees, payment timing, accepted methods, insurance billing, cancellations, and unpaid balances.
- Verify insurance benefits before the first appointment and give clients a written cost estimate.
- Define a late cancellation window, typically 24 to 48 hours, and the fee for missed sessions.
- Review the agreement with each client before the first session and keep a signed copy.
- Notify current clients in writing at least 30 days before any fee change takes effect.
Table of Contents
- Why a Mental Health Practice Needs a Written Financial Policy
- Session Fees, Payment Timing, and Accepted Payment Methods
- Insurance Billing, Coverage, and Client Responsibility for Copays
- Writing a Mental Health Practice Late Cancellation Policy
- Late Payments, Returned Payments, and Delinquent Accounts
- Building an Accessible Sliding Scale Fee Agreement Sample
- Using a Therapy Financial Agreement Template and Getting Client Consent
- Put Your Financial Policy in Writing Before Your Next Intake
- Frequently Asked Questions
Why a Mental Health Practice Needs a Written Financial Policy
A financial policy is a written document that tells clients how the practice charges for services, when payment is due, and what happens when things go wrong. Without one, money conversations happen awkwardly at the front desk, and small disputes turn into lost revenue. Clear rules protect both the practice and the client.
Many practices find that a written policy saves time. Staff stop answering the same questions again and again. Clients know what to expect before their first session, so there are fewer surprises at checkout.
Here is what a strong financial policy usually covers:
- Session fees and how they are calculated
- When payment is due and how it can be made
- How insurance claims are handled
- Cancellation and no-show charges
- Steps taken when a balance goes unpaid
Each of these sections is covered below. The goal is a policy that is short enough to read and clear enough to follow.
Session Fees, Payment Timing, and Accepted Payment Methods
Start with the basics. List your standard session fee, the length of a session, and any other fees, such as fees for evaluations, group sessions, or written reports. Clients should be able to find this information in one place.
Next, state when payment is due. Many practices collect payment at the time of service. Others bill monthly for clients on a payment plan. Pick one approach and write it down.
Finally, list the accepted payment methods. Common options include cash, check, credit card, debit card, and electronic payment. If you keep a card on file, say so and explain how it will be used. Clients should know exactly when their card will be charged.
Insurance Billing, Coverage, and Client Responsibility for Copays
This section matters most for practices that accept insurance. Explain that you will file claims on the client’s behalf, but that the client is responsible for any amount the insurer does not cover. Then walk through the workflow so clients understand what happens before, during, and after a claim.
Be specific about the three main types of client cost:
- Copay: A fixed amount the client pays at each visit.
- Deductible: The amount the client pays before insurance begins to cover services.
- Coinsurance: A percentage of the cost the client pays after the deductible is met.
Verification and estimates before the first session
Run a benefits verification before the first appointment and document what you find: active coverage, mental health benefit, deductible remaining, copay or coinsurance, prior authorization requirements, and telehealth coverage. Give the client a written estimate of what they will likely owe. State plainly that the estimate is based on information available at the time and that final responsibility rests with the insurer.
A common pattern is to verify benefits again at the start of each plan year or whenever a client reports a job or plan change. Put that trigger in your policy so staff know when to re-check.
Claim submission and denials
Set an internal deadline for claim submission and say in the policy that the practice will submit claims promptly. When a claim is denied, explain the appeal process and who is responsible for follow-up. If a denial results from missing information the client needed to provide, such as a new insurance card or a referral, state that the client may be billed for the balance.
Build a claim-submission checklist and assign one staff member to own it.
Out-of-network and reimbursement
If you are out of network, explain that clients may pay upfront and seek reimbursement from their insurer. Offer to provide a superbill with the dates of service, procedure codes, and diagnosis codes the insurer requires. Do not guarantee reimbursement amounts; those are set by the plan.
Coordination of benefits and coverage changes
Ask clients to tell you about any changes to their coverage, including a new plan, a lapse, or a switch to a plan you do not accept. Explain that verifying benefits helps avoid surprise bills, but that coverage is never guaranteed. Insurance rules, approvals, and payment amounts are set by the insurer, not the practice. When coverage changes mid-treatment, document the date, re-verify benefits, and send the client a written summary of the new expected cost before the next session.
Writing a Mental Health Practice Late Cancellation Policy
A late cancellation policy protects the time you hold for each client. Most practices set a window, often 24 to 48 hours before the appointment, and charge a fee if a client cancels inside that window.
Spell out the details:
- How much notice is required
- The fee amount for a late cancellation
- The fee for a no-show, which is when a client does not attend and does not call
- Whether the fee applies to telehealth sessions
- Exceptions for emergencies
Keep the tone warm. Clients are more likely to accept a cancellation fee when they understand that the reserved time could have gone to someone else. Mention that you are glad to reschedule when notice is given early enough.
Take the 2-Minute Billing Audit →
Late Payments, Returned Payments, and Delinquent Accounts
Every practice deals with late payments eventually. Your policy should explain what happens when a balance is past due. Many practices send a reminder, then a second notice, and then discuss a payment plan. Set the timeline and stick to it.
Also address returned payments. If a check or card payment fails, state the fee you charge and how the client can make the payment good. Some practices stop accepting checks from clients whose payments have bounced before.
For accounts that stay unpaid, explain whether you may refer the balance to a collection agency and when that could happen. Be clear that this step is a last resort, and that you will talk with the client first. Practices that handle overdue balances carefully tend to keep more of their clients.
Building an Accessible Sliding Scale Fee Agreement Sample
A sliding scale sets lower fees for clients with limited income. It widens access to care and can be written into your policy as a clear, fair option.
A simple sliding scale fee agreement sample might read:
“Our practice offers reduced session fees for clients with documented financial hardship. To request a sliding scale rate, complete our income form. Approved rates are reviewed every 12 months.”
Include the eligibility process, the documents you will ask for, and how often rates are reviewed. Treat all requests the same way, and keep records that show how each decision was made.
Using a Therapy Financial Agreement Template and Getting Client Consent
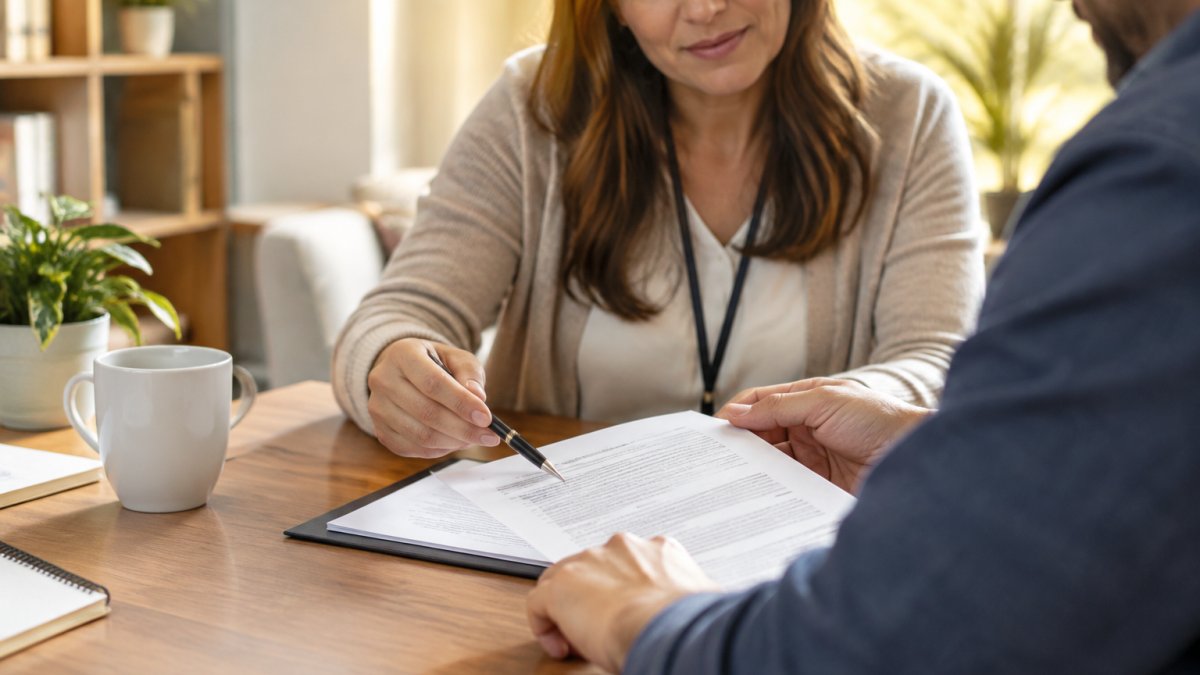
A financial agreement turns the policy into something the client signs. Use a template so every client receives the same information. Include your fees, payment terms, insurance responsibilities, and cancellation rules in plain language.
When and how to explain the policy
Review the agreement with the client before the first session, not at checkout. Walk through the fee, when payment is due, the cancellation window, and what happens if a balance goes unpaid. Give the client time to ask questions and note in the file that the conversation happened. For telehealth clients, review the policy on the video call and send the signed copy through your secure portal.
Documenting acknowledgment
Collect a signed copy and keep it in the client file. If your state or payer requires a specific acknowledgment, check the requirement before you finalize the template. A common pattern is a signature line plus a date and a checkbox confirming the client received a copy. Store the signed agreement the same way you store informed consent documents.
Handling questions and disputes
Designate one staff member to answer billing questions so responses stay consistent. If a client disputes a charge, point to the specific clause in the signed agreement and offer to review the account together. Document the conversation and the resolution in the client file.
Notifying clients of fee or procedure changes
Put a note in the file when the policy changes. Notify current clients in writing, email or portal message is typical, at least 30 days before a fee change takes effect, and ask them to sign the updated version. State the effective date and what changed. This creates a clear record and avoids confusion later. If a client declines the new terms, explain the options, including referral, before the change takes effect.
Watch out: A policy change announced at the front desk or only in a newsletter is easy to miss and hard to enforce. Send it directly to each affected client and keep proof of delivery.
Put Your Financial Policy in Writing Before Your Next Intake
A written financial policy takes time to build, but it saves far more time than it costs. Start with the sections above, adapt them to your practice, and have every new client review and sign the agreement at intake.
If you want help turning this into a working system, Healthcare Partners Consulting and Billing supports mental health group practices with billing, credentialing, and intake workflows. Take the 2-Minute Billing Audit to see where your current process is costing you money.
Frequently Asked Questions
What components should be included in a practice’s financial policy?
A solid mental health financial policy covers session fees, accepted payment methods, when payment is due, your insurance billing responsibilities, the client’s share of copays, deductibles, and coinsurance, cancellation and no-show fees, late payment procedures, and any returned payment charges. Include a sliding scale or payment plan section if you offer one. Put the policy in plain language, have each client sign it at intake, and review it with them before treatment begins so that expectations about money are clear from the first session.
How do you handle late cancellation fees in a financial policy?
State the notice period required, such as 24 or 48 hours, the exact fee amount in USD, and whether the fee applies to no-shows as well. Explain how the fee is charged, for example to a card on file, and note any exceptions for emergencies. Set an amount that fits your session fee and state it clearly so clients can follow it without confusion.
Should a financial policy include information on insurance verification?
Yes. Explain that you verify benefits before the first session when possible, that clients are responsible for providing accurate insurance information, and that unpaid balances resulting from non-covered services or inactive coverage are the client’s responsibility. Describe how you handle out-of-network status and whether you will bill the client directly if a claim is denied. Clear wording here prevents most billing disputes.
Are sliding scale agreements required in a standard financial policy?
They are not legally required in most cases, but a sliding scale option is useful for clients facing financial hardship and helps show that your practice is accessible. If you offer one, include the eligibility criteria, the documentation you may request, how the reduced fee is set, and how long it lasts before it is reviewed. Keeping this in writing protects both the client and the practice.
